
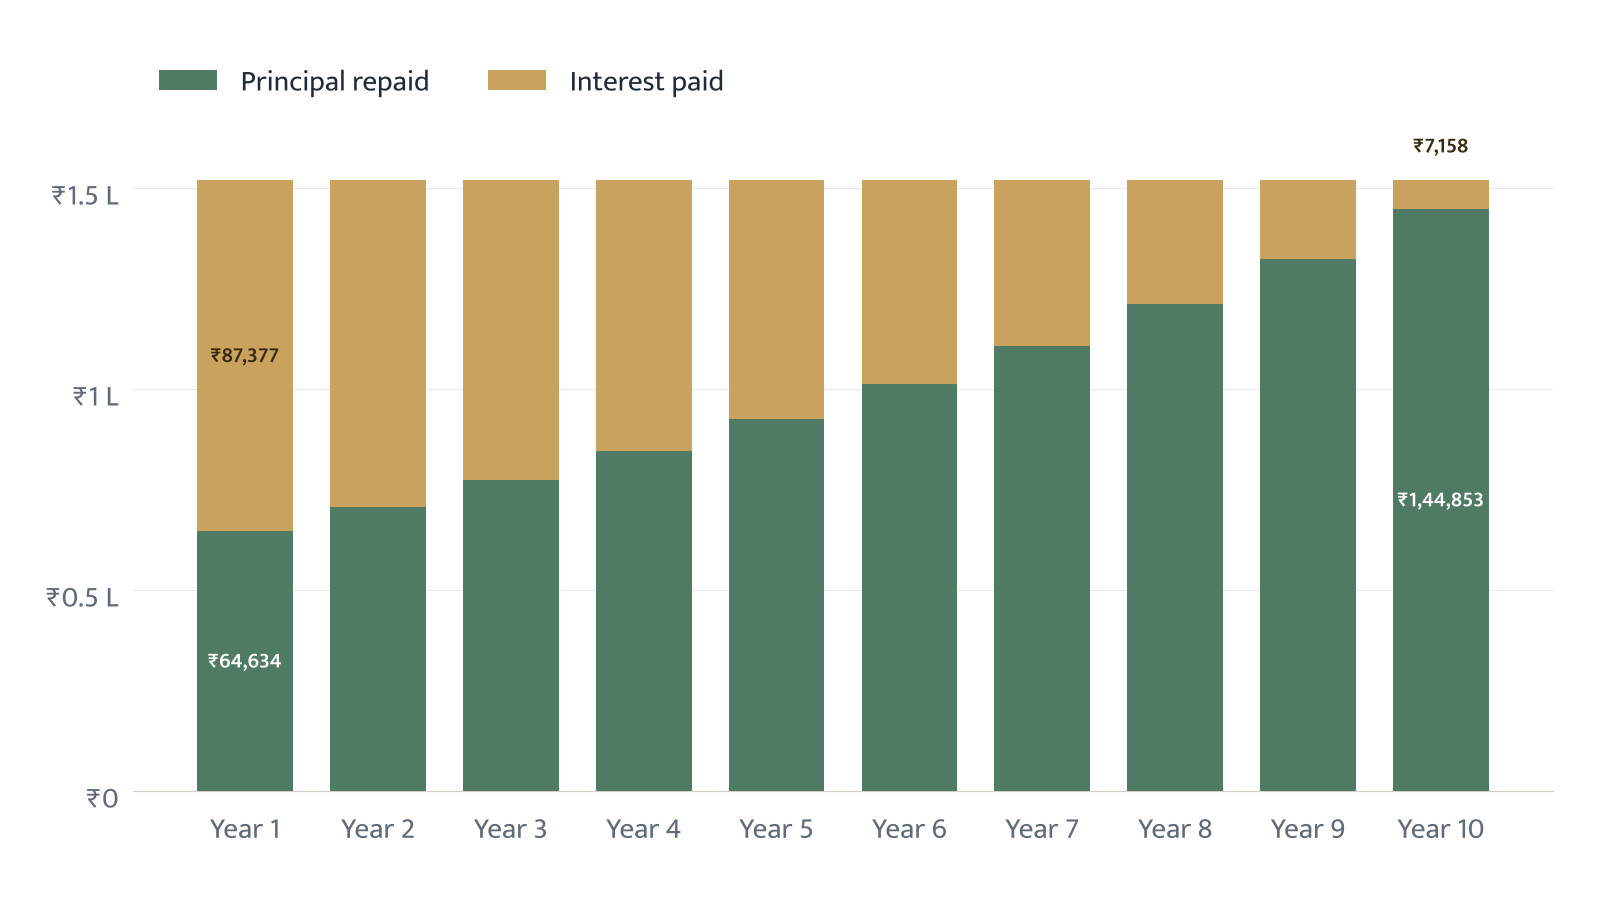
An EMI (equated monthly instalment) is the fixed amount you pay the lender every month until the loan is closed. Each EMI has two parts: interest on the amount you still owe, and a repayment of principal. The total stays the same, but the split between the two changes every month.
The formula#
EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1)
P is the loan amount, r is the monthly interest rate (the annual rate ÷ 12 ÷ 100), and n is the number of monthly instalments.
Banks use this reducing-balance method: each month's interest is charged only on the principal still outstanding, not on the original loan amount.
A worked example#
Worked example
₹10 lakh home loan for 10 years
- Loan amount (P)
- ₹10,00,000
- Interest rate
- 9% a year (example rate)
- Monthly rate (r)
- 0.75%
- Instalments (n)
- 120
- Work out (1 + r)^n: 1.0075 raised to the power 120 is about 2.451357.
- Multiply P × r × (1 + r)^n: ₹10,00,000 × 0.0075 × 2.451357 ≈ ₹18,385.18.
- Divide by ((1 + r)^n − 1) = 1.451357: ₹18,385.18 ÷ 1.451357 ≈ ₹12,667.58.
EMI ≈ ₹12,667.58 a month
| Item | Amount |
|---|---|
| Monthly EMI | ₹12,667.58 |
| Total of all EMIs | ₹15,20,109 |
| Total interest paid | ₹5,20,109 |
| Interest in the first EMI | ₹7,500.00 |
| Principal repaid in the first EMI | ₹5,167.58 |
Where your first EMI goes#
In the first month, interest is 0.75% of the full ₹10,00,000, which is ₹7,500. Only ₹5,167.58 of your first EMI reduces the loan. As the balance falls, the interest part shrinks and the principal part grows.
How the split changes over the years#
Over the first year you pay about ₹87,377 in interest and repay about ₹64,634 of principal. By the tenth year, interest is down to about ₹7,158 and almost the whole EMI goes towards the loan.
Why this matters for prepayment#
Because interest is heaviest in the early years, a prepayment made early saves far more interest than the same prepayment made near the end. When you prepay, most lenders let you choose between a lower EMI or a shorter tenure. Keeping the EMI and shortening the tenure usually saves more interest.